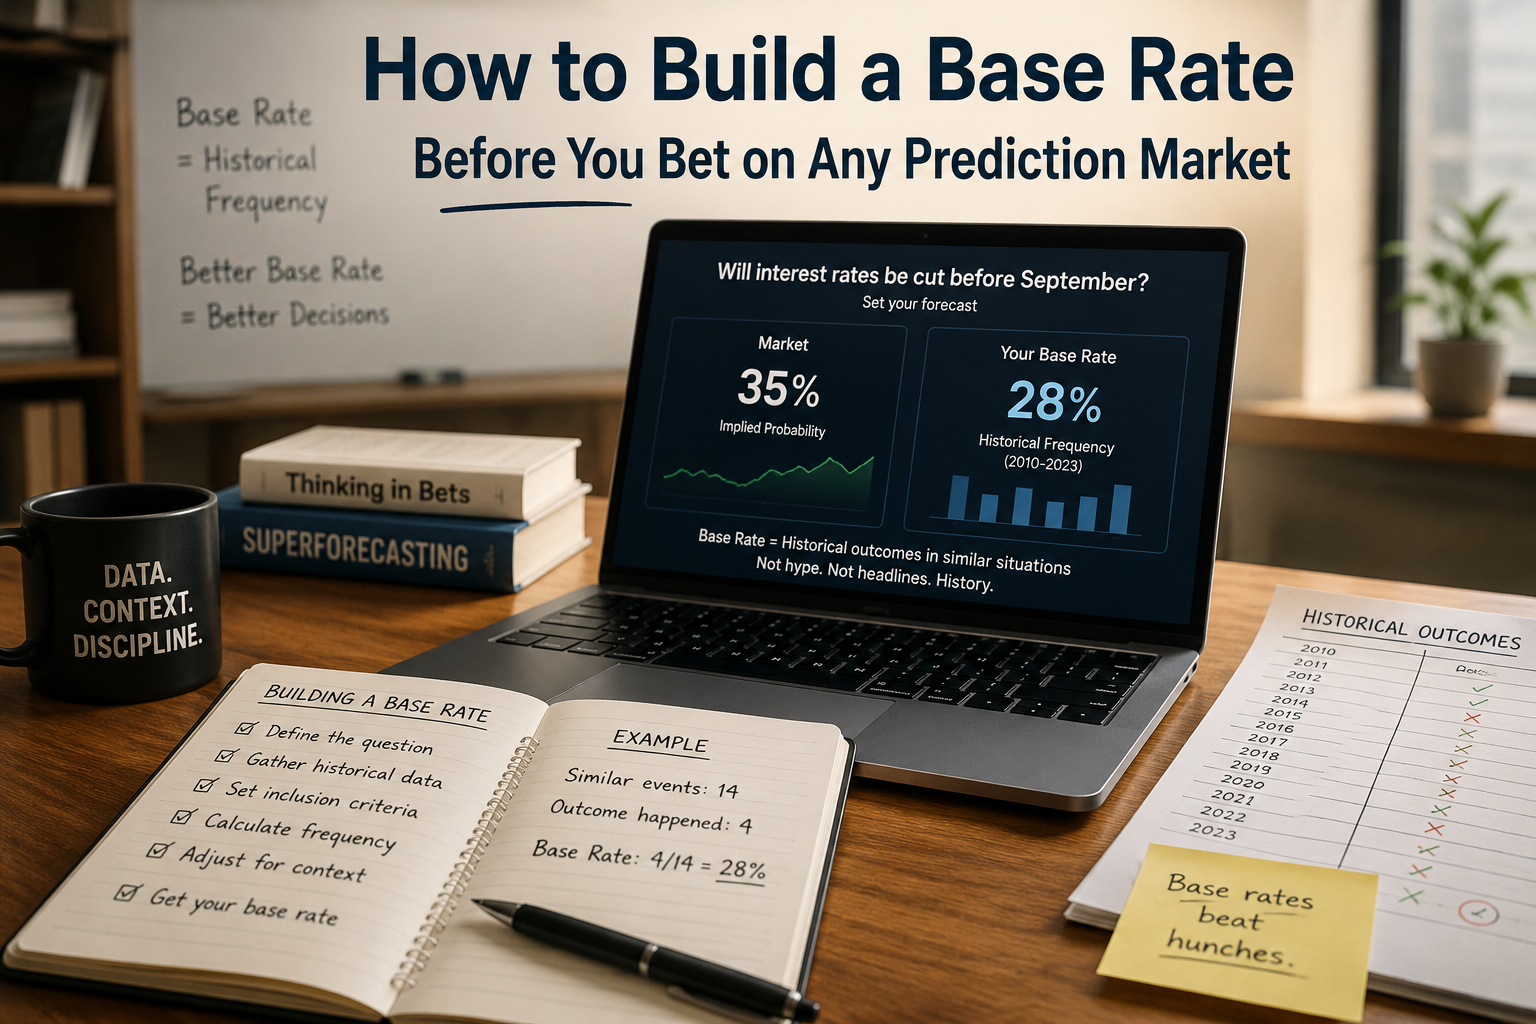
Before you ever look at what a prediction market is pricing, you need your own number to compare it against. That number is called a base rate, and building one correctly is the single most important skill in finding mispriced markets.
What Is an Event?
In prediction markets, an “event” is the specific, resolvable question a contract is tied to — for example, “Will the Fed cut rates in September?” or “Will Candidate X win the primary?” Every event has a defined resolution date and a clear yes/no (or multi-outcome) condition. Your job isn’t to guess the event in isolation — it’s to figure out how often events like this one have happened before.
It helps to break an event down into its components before you go looking for comparisons: the actor (who or what has to do something), the action (what has to happen), the timeframe (by when), and the resolution source (who decides and how). Two markets that look similar on the surface — “Will the bill pass by June?” versus “Will the bill pass this session?” — can have very different true probabilities once you notice the timeframe differs. Precision at this stage saves you from building a base rate for the wrong question entirely.
What Is a Reference Class?
A reference class is the group of similar past events you use to estimate a probability.Your reference class could be “all Fed Chair nominees confirmed by the Senate in the past 40 years”, and you’d be asking, “Will this Fed Chair nominee be confirmed? The secret lies in making sure you select a class whose members are not too broad (such as all the political confirmations, thus losing the relevance of the detail) and not too narrow (such as only this particular nominee, so that you don’t have any data points).
Good reference classes share the structural features that actually drive the outcome — similar stakes, similar procedural rules, similar political environment — not just superficial similarity.
Calculating a Base Rate
Once you have a reference class, the calculation itself is simple :
Base rate = (number of times the outcome occurred) ÷ (total number of comparable events)
If 34 of the last 40 Fed nominees were confirmed, your raw base rate is 34/40 = 85%. That’s your starting point not your final answer. You then adjust it up or down based on case-specific facts the base rate doesn’t capture — a controversial nominee, a split Senate, unusual political pressure. This two-step process (start with the base rate, then adjust) prevents you from over-weighting a single narrative headline, which is the most common way traders overpay for “story-driven” markets.
Comparing Your Estimate to Market Odds
Prediction market prices are, by design, implied probabilities. A contract trading at $0.62 is saying the market believes a 62% chance of “yes.” Once you have your own adjusted base rate — say 78% — you compare the two directly:
Edge = Your estimate − Market-implied probability
Here, 78% − 62% = 16 percentage points of potential edge. That gap is your signal, not a guarantee. Small gaps (a few points) are usually just noise or transaction costs. Larger, persistent gaps — especially ones you can explain with a clear reference class and reasoning — are where mispricing tends to live.
The Takeaway
A base rate isn’t a magic number pulled from intuition — it’s a disciplined starting point built from real historical frequency, adjusted for what makes this specific event different. Skip this step and you’re just trading on vibes; do it well and you have an actual edge to size against.